

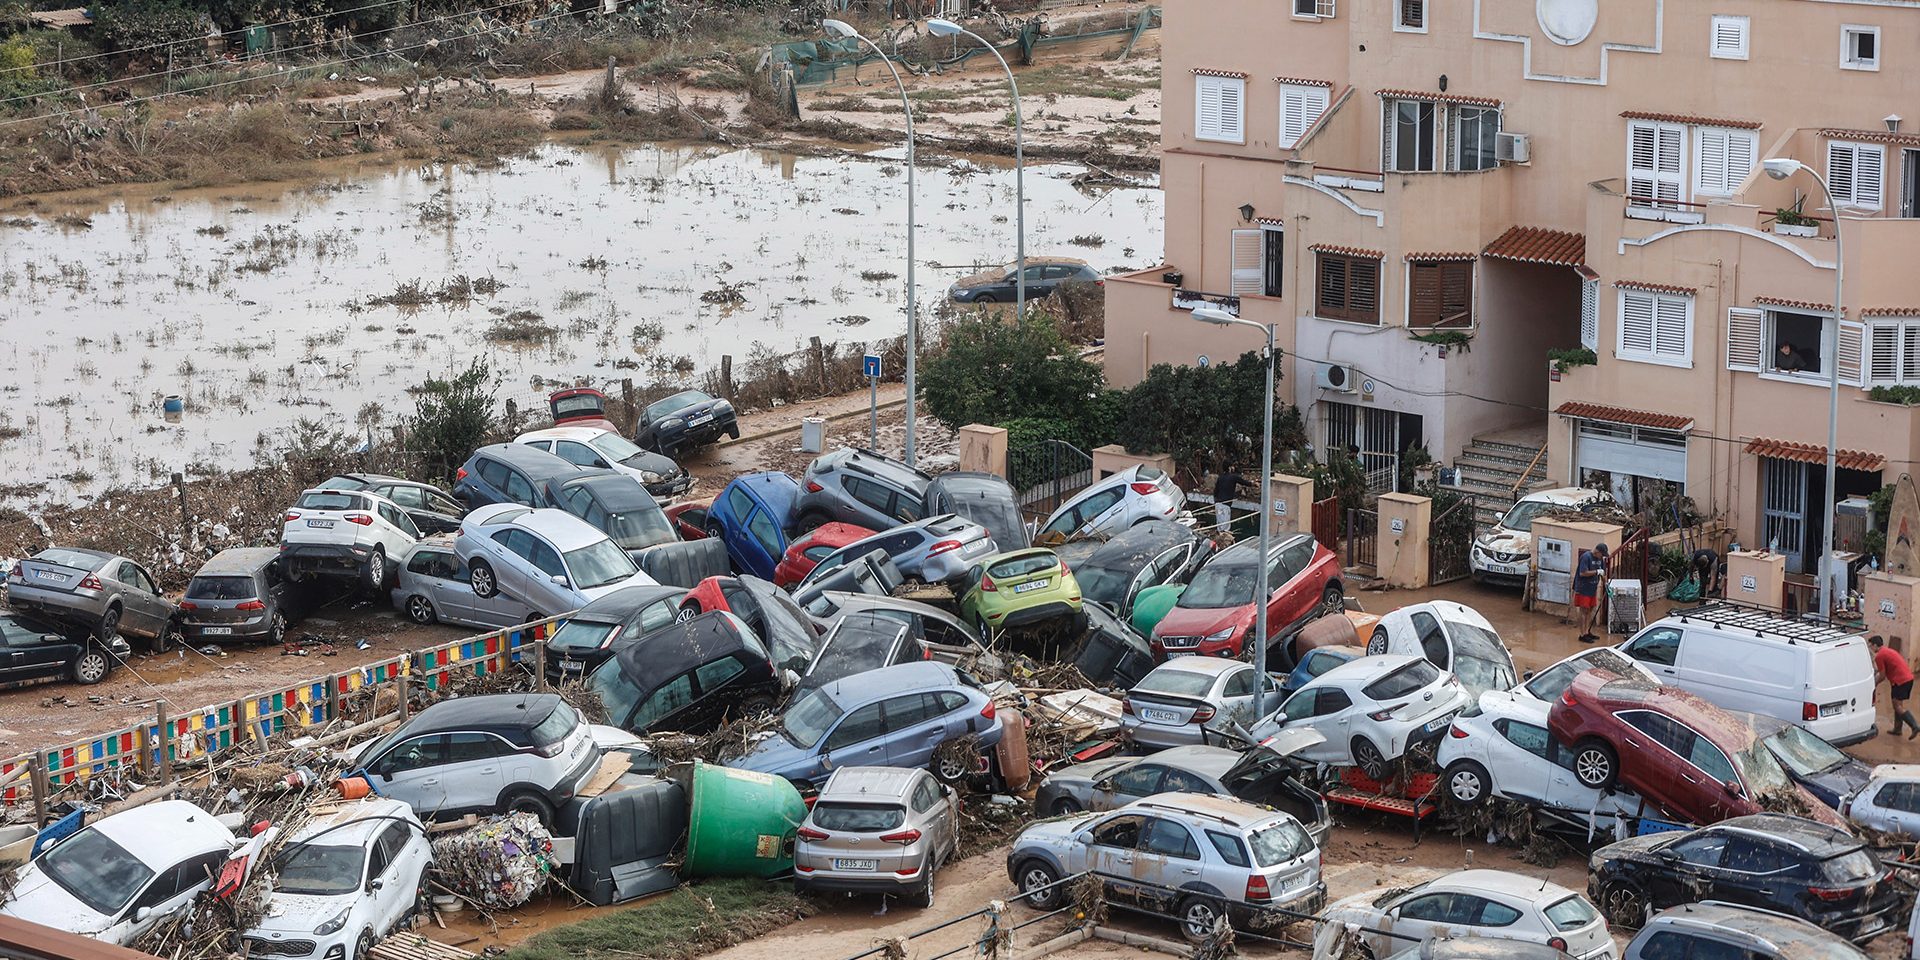
The devastating effects of the DANA that affected several municipalities in Spain have led to the adoption of a series of fiscal measures by the government. The measures were approved by Royal Decree-Laws 6/2024 of 5 November and 7/2024 of 11 November. The main provisions that have been implemented to support the self- employed, companies and taxpayers affected by the natural disasters are detailed below.
1. Direct Aid to the Self-Employed and Companies Taxpayers of Personal Income Tax (IRPF) or Corporate Tax, provided that their tax domicile is located in the municipalities affected by the DANA, or that they have establishments or holdings in these areas, even if they do not reside there for tax purposes. In the case of companies, the amount of the aid will depend on the volume of operations during the financial year 2023 and in the case of entrepreneurs or professionals who are natural persons, the amount of the aid will be 5,000 euros.
This aid can be applied for between 19 November and 31 December 2024 through the Tax Agencys electronic headquarters.
2. Extension of Deadlines for Filing Tax Returns
For taxpayers whose deadline for filing returns and self-assessments is between 28 October and 31 December 2024, an extension until 30 January 2025 has been approved.
3. Special Deferral of Payment of Debts
The possibility of requesting a special deferral for the payment of taxes has been made available, which allows for a deferral of up to 24 months without interest on late payment during the first six months, for tax returns due between 28 October and 30 January.
4. Extension of the Payment Deadline until 5 February 2025
The second payment of Personal Income Tax (IRPF) corresponding to the financial year 2023, for taxpayers with tax domicile in the province of Valencia and the municipalities affected by the DANA.
Tax debts in the voluntary and executive periods, as well as the expiry of payment deadlines and fractions of deferment agreements already granted, whose deadline has not expired by 7 November 2024.
5. Taxpayers in modules who carry out their economic activity in affected areas.
25% reduction in the net yield of the modules in Personal Income Tax (IRPF). In Value Added Tax (VAT), a 25% reduction will be applied to the tax payable on current transactions.
In addition, taxpayers may exceptionally renounce the module system during the month of December 2024, opting to pay tax under the simplified direct assessment system.
6. Exemption from Real Estate Tax (IBI) and reduction of the Business Activity Tax
(IAE).
Exemption from Property Tax (IBI) is established for those properties located in the municipalities affected by the DANA. Likewise, entities and professionals with business premises in the affected areas will see a proportional reduction in the amount of the Economic Activities Tax (IAE) for the year 2024.
Taxpayers who have already paid this tax may request a refund of the corresponding amount.
Finally, it should be noted that the municipalities affected by the DANA include the Malaga municipality of Alhaurín de la Torre.